










Trade & industry report with cap/hpi motorcycle editor Alan Elsworth.
New Market
Although feedback suggests lower footfall in showrooms this year, retailers are reporting that customers visiting stores are mostly buyers rather than tyre kickers. Hopefully, the few who are kicking tyres will become buyers in the months ahead! Still, registrations show a decline of 13.1% to 9848, from 11,327 in April last year in the latest MCIA new registration figures.
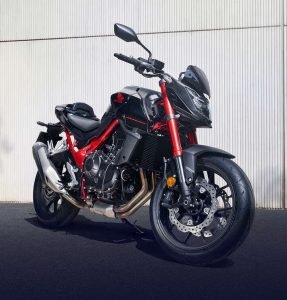 The new Honda CB 750 Hornet topped the 751-1000cc sector with 119 leaving showrooms in April. It also helped the naked sector to achieve a quarter share of the total motorcycle market
Drilling down into the figures, it is difficult to find a real positive. The moped sector is continuing its sharp retreat, with both month and year-to-date sales seeing over a third fewer registrations than 2022. After a good performance in March with the new plate, motorcycles were down 12% in April, but there was less of a loss year-to-date, with registrations for the four months down 2.1%. The naked sector represented a quarter of total market share in April.
Again, in the engine size tables, there is little to be optimistic about, except for the 751-1000cc sector, which was up 15.2%. At the opposite end of the capacity scale, the learner legal sub-125cc bands are falling behind the numbers seen during the pandemic as they start to re-align to pre-Covid levels. One positive is that larger capacity machines tend to be bigger ticket and therefore more profitable for dealers.
ACEM, the European manufacturers association, recently released its Q1 registration numbers for Europe’s Key Markets, giving us a chance to benchmark our domestic market against the top five continental markets, both in ICE and electric sectors. The comparison doesn’t make for pleasant reading, with all the mainland European key markets starting the year off stronger than the UK.
Used Market
As already mentioned, customer traffic through showroom doors has been lower than is comfortable, but used bike sales are still happening at a reasonable rate. Where the used market will go in the coming months is not easily predictable, but it’s an important question as stock levels will reflect demand and prices.
Over the next few months, we should get some clarity about where prices are heading, bearing in mind that the season is already halfway through. Seasonal lower volume turnover is around the corner, and reported prices, when discussed during our latest research, are at the mid-season level, where, except for a few corrections the market suggests, generally little movement is required either way.
Auction Overview
The auction system still needs to see larger quantities of entries, as would have been the case five years ago. The volume of bikes in the system has declined steadily since the shortage of used machines started in the trade during the pandemic, from circa 400 machines per month to around only 200.
A recent big sale involving Black Horse and BMW disposals, via BCA, had a much-reduced entry list (fewer than 70 bikes), but the good news is that it achieved a higher sold rate of 79% and an overall auction average price of 101%, compared to the CAP current used reported figures.
The upshot of fewer bikes is good news for anyone writing future agreements, as the hope of better trading conditions will increase used sales in a market that is still struggling to supply. To that end, figures have remained robust.