











A landslide Labour general election victory followed on the heels of another grim first six months of trading in 2024 for the UK bike business. And one is set to make some facets worse for the other going forward. BDN financial editor Roger Willis reports.
Total registrations for the period festered, 0.7% down at 61,818. Still overwhelming dominant gas-guzzler kit was slightly further adrift, falling by 0.8% to 59,891.
By far the largest sector, encapsulating up-to-125cc mobility and last-mile delivery products, retreated by 3.2% to 19,773. And the really bad news is its decline is now ripe for acceleration once Keir Starmer and his comrades get their feet tucked under the legislative table.
An early warning notice from Team Starmer is forthcoming abolition of the zero-hours contracts upon which gig economy delivery and home hospitality operators depend. This will throw a massive spanner into their works and almost certainly undermine related scooter sales.
And while deleterious inflation may have already dropped to the Bank of England’s 2% target, it doesn’t go backwards. The cost of living remains excruciatingly high, as those who struggle to afford groceries will affirm, and impinges on the wider populace’s ability to make large discretionary purchases – such as motorcycles.
Ironically, an indicator of how money is now often too tight to mention is the burgeoning success of the only motorcycle capacity class to display growth with gusto. The 126-500cc sector is now our second-biggest market, 23.7% up 11,498 units over the past six months, a budget bargain bonanza for impecunious enthusiasts rather than the A2 licence holder group.
Beyond that glimmer of hope are layers of gloom. 501-750cc machines have sunk by 8.5% to 7352. Last year’s 751-1000cc boom, which had boasted 26.8% growth to 11,470 at the halfway stage, is 5.7% down to 10,812. Top-notch 1000cc-plus sales, which were already easing backwards by 1.2% to 11,129 in June 2023, are now showing a 6% retreat at 10,456.
Labour’s chancellor of the exchequer Rachel Reeves, the first-ever UK Treasury headmistress, assures us that she is taking immediate action to fix Britain’s crumbling economic foundations. “By growing our economy, we can rebuild Britain and make every part of the country better off,” Reeves has promised. We have yet to be convinced.
Six months’ winners and losers
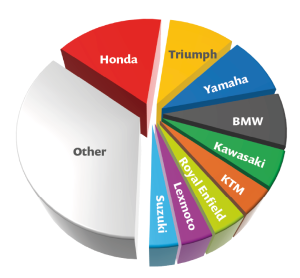 Jan-Jun 2024 major brands market share
Based on MCIA charts destined for press consumption, covering the full six months to June 2024, we have been able to extract the overall sales performance of nine leading brands in order of volume. Seven of these also display calculated growth or losses versus the six months to June 2023. That information is absent for Lexmoto and Suzuki because the former failed to achieve a chart presence in March 2023, and the latter went AWOL in February 2023, so movement indication data was incomplete.
We have many qualifications about the extent to which headline numbers represent success in what has been a challenging market. For instance, not only have Honda and Yamaha sales faded by a greater degree than the industry’s six-monthly average shortfall, but in both cases, approximately a third of each brand’s entire transactional traffic also involved low-margin products up to 125cc.
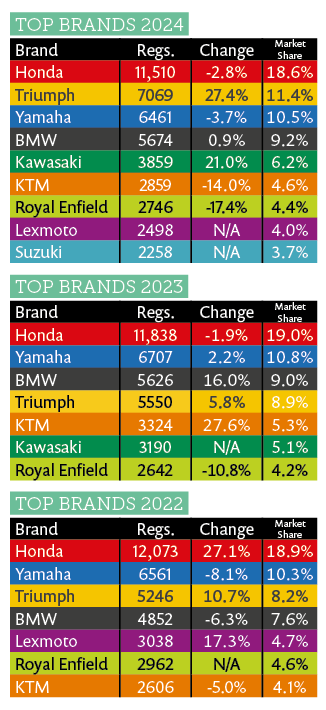 On the face of it, Triumph did much better. But muscular double-digit percentage progress was driven by roughly a couple of thousand low-margin offerings – the company’s new single-cylinder Speed 400 and Scrambler 400X range. Without those, Hinkley’s retail headcount would be below the 5550 bikes sold in 2023’s first half. BMW Motorrad didn’t comprehensively shine, either. A fairly gestural gain equated to just an additional 104 bikes despite rolling out what was supposed to be a pivotal new R1300 GS model loaded with bells and whistles at the back end of last year.
However, Kawasaki roundly deserved bragging rights, having finally restored stock levels and studiously avoided a surfeit of upmarket pricing to spur a double-digit percentage surge. The same cannot be said for KTM. You can read about its parent Pierer Mobility’s “profit warning” confession of erratic inventory, dealer funding issues, consequent sales decline, etc, elsewhere in BDN this month.
We’ve also recently covered Royal Enfield’s UK operation turnaround since separation from distributor MotoGB, which is now bearing fruit. With stock access steadily improving, the distinct advantage of budget price points and a steady stream of new models, what’s not to like? Dealers may never get mega-rich selling Royal Enfield wares, but they’re unlikely to go bust.
Finally, Lexmoto has pulled its Chinese socks up to rejuvenate bargain-basement appeal that it can meet with fresh stock. Although our data is semi-anecdotal, we estimate somewhere around 50% growth in the six months of 2024 to date – admittedly from a low base. However, Suzuki’s bounce-back seems to have stalled. A judicious guesstimate puts it more than 20% in arrears.