











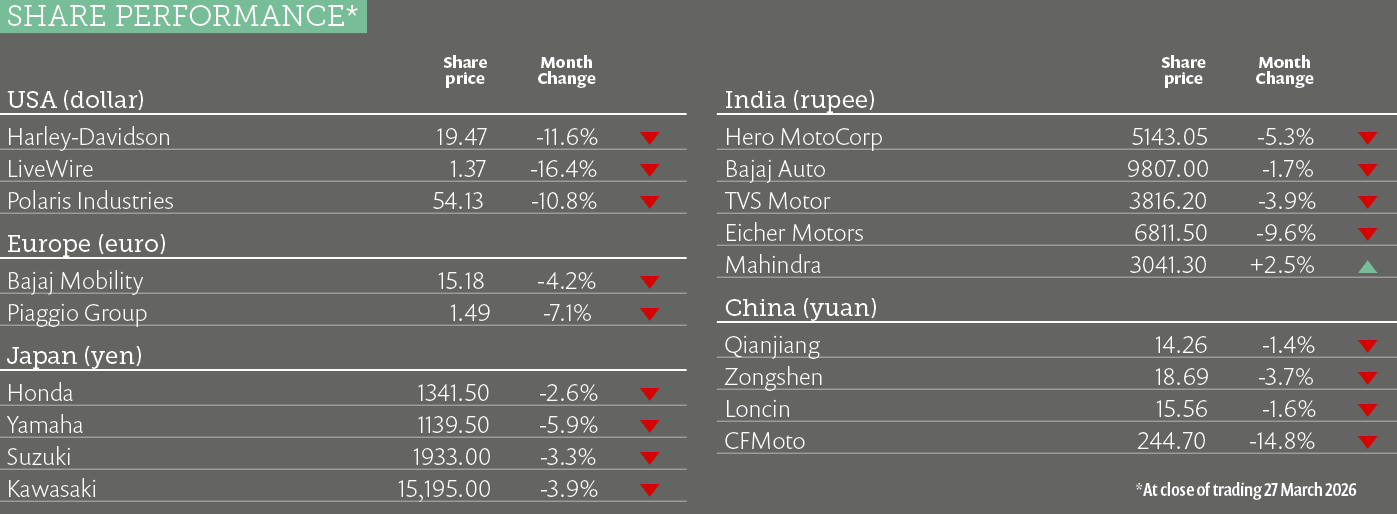
A snapshot of key motorcycle industry share performance at the trading closure on Friday 27 March
USA
Harley-Davidson has had a rough time throughout March, its share price consistently failing to climb back into $20-plus territory and averaging a monthly loss of approximately 11.6% in value. Bad news kicked off with a plunge to $17.60 on 2 March and then a lowest point of $17.18 on 18 March. Gradual easing towards the end of the month saw a best of $19.47 at the close on Friday, 27 March. Harley investors must now be saying their prayers for a maintenance of that trajectory going forward into April. Harley’s LiveWire electric spin-off business suffered far worse, rattling along near the market’s bottom step. Its 2 March starter price was a mere $1.53, before sinking to a $1.205 nadir on 20 March and a Friday 27 March close of $1.37 – despite a big promotional effort featuring one-off customised specials of the brand’s latest S2 Alpinista model.
Polaris Industries is on the receiving end of a US Congressional bill that could leave its last remaining “motorcycle” product in limbo. This seeks to change the Federal motorcycle definition to exclude certain three-wheeled vehicles currently regulated as motorcycles. Most notably, the Polaris Slingshot will be the biggest brand affected, because it features a steering wheel and bucket seats. If the bill passes, narrowing the definition of a motorcycle, a rider will henceforth be required to sit astride a seat or saddle, steering by a handlebar, and employing handlebar and foot controls. The US Motorcycle Industry Council is the principal opponent of the bill, arguing that it would result in immediate withdrawal of certain product lines from the market, harming manufacturers and dealerships.
EUROPE
Bajaj Mobility and its now wholly-owned KTM operation is still clearly suffering from a lack of free-float euro stock availability for speculative investors, particularly those seeking Dax listings in Frankfurt. The stock price has fallen widely in the past month, both euro-quoted in Frankfurt and Vienna, and Swiss Francs in Zurich. Reluctance to expose maximum control by the Indian parent is almost certainly to blame.
Piaggio Group has seen its shares in Milan deteriorate steadily in value during the past month, in the wake of poor full-year financial results.
JAPAN
Honda is facing its first annual loss since the 1950s (see page 62 in this issue). The company is anticipating a net loss of between ¥360bn and ¥630bn in full-year results due after the end of March, following an announcement to scrap three key EV models planned for production in North America. It has just become the latest global automotive giant to be stung by a dramatic slowdown in the expansion of the US EV market under the Trump administration, which has cancelled environmental regulations and subsidies supporting the uptake of battery-powered vehicles. And it’s also on the receiving end of aggressive US tariffs. A plan targeting 100% battery and fuel-cell vehicle sales by 2040 is to be abandoned. How this will affect any roll-out of powered two-wheelers is unclear.
INDIA
HMSI, Honda’s huge wholly owned presence in India, is making the sub-continent’s big news, casting a long shadow over its five big-league listed motorcycle manufacturers, and blowing the wind up market leading Hero MotoCorp’s skirt in particular. HMSI is adding a new 670,000-unit production line to its Tapukara plant, taking output there to more than two million units annually, and will soon have a fourth production line in operation at the Gujarat HMSI plant – already Honda’s largest bike manufacturing facility anywhere in the world. Taken together, their output will reach more than eight million units per year by 2028. While Hero, Bajaj Auto (and its Bajaj Mobility Austrian enterprise), TVS Motor, Eicher’s Royal Enfield and BSA-armed Mahindra all have some international clout, none of them are remotely in the same league as monumentally rapacious Honda. Mahindra, incidentally, has just abandoned its long-term agricultural tractor marketing presence in Japan.
CHINA
An almost endless stream of Chinese motorcycles is now invading the UK market, many with their original branding intact and increasingly muscular reputations. This month’s stand-outs have to be Qianjiang’s 16-model strong QJ Motor offerings – with Keeway and Benelli coming from the same stable. From Loncin, there’s the strengthening Voge array and Zongshen filling out Lexmoto’s catalogue. CFMoto is to the fore, of course, as is an extending list including Mondial, AJS, Kove and Zontes. Front-rank distributors include MotoGB and Moto73. We don’t need to look much further for a welcome boost for the UK’s recently struggling market, even if the Chinese manufacturing resources aren’t exactly wallowing in lolly.